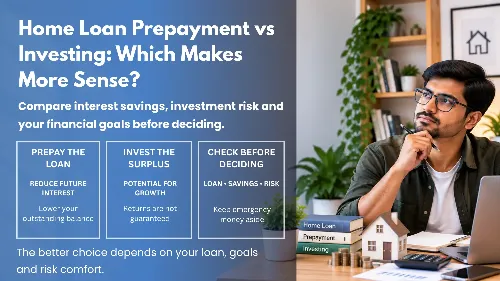
Have a ₹40 lakh home loan and extra money? Compare prepayment and investing with simple numbers, tax points and practical checks.
You have a ₹40 lakh home loan and some extra money in your account. It may be a bonus, savings, an FD maturity amount or money received from another source.
Now comes the common question: Should you use that money to prepay the home loan or invest it?
Both choices can make sense. Prepayment can reduce the interest you pay on the loan. Investing can help your money grow, but investment returns are not guaranteed.
First, Look at the ₹40 Lakh Home Loan
Suppose the home loan is ₹40 lakh at 8.5% interest for 20 years. This is a FinToolBaba calculator scenario used only to understand the numbers. It is not a real customer's loan.
| Loan Detail | Value |
|---|---|
| Loan amount | ₹40 lakh |
| Interest rate | 8.5% p.a. |
| Loan tenure | 20 years |
| Monthly EMI | About ₹34,713 |
| Total interest over full tenure | About ₹43.31 lakh |
This shows why a long home loan can become expensive. A borrower may take ₹40 lakh, but continuing the loan for the full 20 years can mean paying a large amount of interest.
Your actual EMI and total interest will be different if your loan amount, interest rate or remaining tenure is different.
You can check your own EMI, total interest and repayment cost using the FinToolBaba Mortgage Calculator.
What Happens When You Prepay?
Home loan prepayment means using extra money to reduce the outstanding loan amount.
For example, if your outstanding loan is ₹35 lakh and you make a ₹2 lakh part-payment, the outstanding amount can fall to about ₹33 lakh, subject to the lender's calculation.
After a prepayment, the lender may reduce the EMI, reduce the remaining tenure, or provide the applicable options under the loan terms.
If your main goal is to save interest, keeping the EMI similar and reducing the loan tenure can often give a bigger interest saving than simply reducing the EMI.
You can check the actual effect of different prepayment amounts using the FinToolBaba Loan Prepayment Calculator.
What If You Invest the Money Instead?
The other option is to keep the home loan running and invest the extra money.
The idea is simple. Instead of using the money to reduce the loan, you keep it invested and allow it to grow over time.
But there is an important difference between the two choices.
The saving from loan prepayment is linked to your loan terms. Investment returns are not guaranteed.
A market-linked investment can rise in value in some years and fall in others. Even if an investment has delivered good returns in the past, that does not mean the same return will continue in the future.
So comparing an 8.5% home loan with an expected 10% or 12% investment return is not enough to make the decision.
You can use the FinToolBaba SIP Calculator to compare different investment assumptions instead of relying on one expected return.
Prepaying vs Investing: The Simple Difference
| If You Prepay | If You Invest |
|---|---|
| Loan balance goes down | Investment stays invested |
| Future loan interest can reduce | Money may grow over time |
| Saving depends on your loan | Return is uncertain |
| Loan can finish earlier | Investment value can rise or fall |
| Debt burden becomes lower | There is potential for higher growth |
So the question is not simply, “Which percentage is higher?”
The better question is whether you prefer the more certain saving from reducing your loan or are comfortable taking investment risk for the possibility of higher growth.
When Prepayment May Make More Sense
Prepayment may be worth considering when:
- Your home loan interest rate is relatively high.
- You still have many years left on the loan.
- You want to become debt-free sooner.
- Your EMI feels heavy on your monthly income.
- You are not comfortable taking market risk with the surplus.
Timing also matters. A prepayment made earlier in the loan can reduce interest for a longer remaining period.
If you want to understand how the timing of prepayment affects the saving, you can read Best Time to Prepay Your Home Loan: Early vs Late Years.
When Investing May Make More Sense
Investing the surplus may be worth considering when:
- Your home loan rate is relatively low.
- You already have enough emergency savings.
- You can keep the investment for several years.
- You understand that market-linked investments can fall.
- You have other long-term financial goals.
Do not assume that the investment will definitely earn more than the home loan costs.
For example, an assumed 11% return can be used for a calculation, but it does not mean the investment will actually give 11% every year.
Do Not Use All Your Savings for Prepayment
This is an important point that is easy to miss.
Suppose you have ₹5 lakh available and use the full amount for home loan prepayment. Your loan balance will fall, but you may also be left with very little cash.
If a medical expense, job loss, family emergency or major repair comes up, you may need money quickly.
What About Home Loan Tax Benefits?
Tax can also affect the decision, especially if you currently claim eligible home-loan deductions.
Under the current Income Tax Department guidance for the old tax regime, eligible interest on a home loan for a self-occupied property can qualify for a deduction under Section 24(b), subject to the applicable conditions and limits. For such a property, the stated maximum is ₹2 lakh. Eligible housing-loan principal can also fall under Section 80C within the combined ₹1.5 lakh limit.
The rules are not the same for every borrower. Tax treatment can depend on the tax regime, property type, loan purpose and other conditions.
Also, prepayment reduces future loan interest. Therefore, the amount of interest-linked tax benefit available in future can also change.
Before making a large prepayment, check the latest rules on the Income Tax Department website.
Check Your Loan Terms Before Paying
Do not assume that every home loan has exactly the same prepayment rules.
Before making the payment, check your loan agreement, current outstanding balance, interest rate and any applicable charges or conditions.
The RBI's consumer guidance also recommends checking important loan terms such as the interest rate, whether the loan is fixed or floating, reset terms and applicable fees, including prepayment-related charges.
You can check the official RBI Home Loan FAQs for borrower-related guidance.
You Do Not Have to Choose Only One
There is another option: split the surplus.
One part of the money can be used for home loan prepayment, while another part can remain invested.
This can work for someone who wants to reduce debt but also wants to continue building long-term investments.
For example, instead of putting the entire surplus into one option, a borrower may decide on a split after keeping emergency savings aside.
The right split depends on income, emergency savings, loan rate, remaining tenure, investment period and comfort with investment risk.
If you want to compare the broader prepay-versus-invest decision, you can also read Should You Prepay Your Loan or Invest the Lump Sum Instead?.
Four Numbers to Check Before Deciding
Before making the final decision, write down these four numbers:
- Current outstanding home loan balance.
- Current home loan interest rate.
- Remaining loan tenure.
- Amount available for prepayment or investment.
First calculate how much interest the prepayment can save. Then compare the same amount with a realistic investment calculation.
This is better than following a general rule such as “always prepay” or “always invest”.
Frequently Asked Questions
Is prepaying a home loan better than investing?
Not always. Prepayment gives a more certain saving on future loan interest, while investing gives the possibility of higher growth but also carries investment risk. The loan rate, investment period, tax position and risk level all matter.
Does home loan prepayment reduce total interest?
Yes. A prepayment reduces the outstanding principal, which can reduce future interest. The exact saving depends on the outstanding balance, interest rate, remaining tenure and amount prepaid.
Should I reduce EMI or loan tenure after prepayment?
If the main goal is to save more interest and your monthly budget allows it, keeping the EMI similar and reducing the tenure can be more effective. The options available from the lender also matter.
Should I use all my savings to prepay the home loan?
No. Keep enough money for emergencies and near-term expenses first. Using all available cash for prepayment can leave you without an easily accessible financial cushion.
Can I invest and prepay the home loan at the same time?
Yes. You can divide your surplus between prepayment and investment. This can help reduce debt while continuing to work towards long-term financial goals.
Does tax affect the prepayment decision?
It can. Home-loan deductions depend on the applicable tax regime and other conditions. Prepayment also reduces future interest, so check your individual tax position before making a large payment.
Check Your Own Numbers
A ₹40 lakh home loan can look very different depending on the interest rate and years remaining.
Do not decide only from someone else's example. Start with the Mortgage Calculator to understand your EMI and total loan cost.
Then use the Loan Prepayment Calculator to see the interest saving from a lump-sum payment, and the SIP Calculator to compare different investment assumptions.